Will deflation doom stocks?
If prolonged logic dictates it will.
Lower cost = lower earnings = lower prices AND higher real rates = good
alternative to stocks = lower valuations.
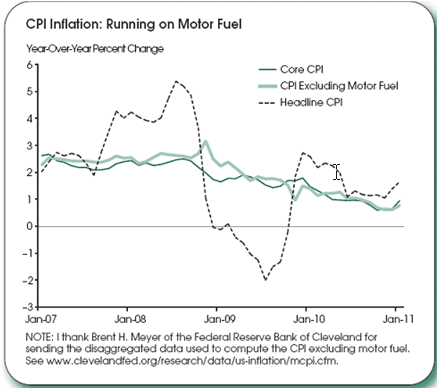
This is why looking at the latest CPI numbers it’s at least a tad
concerning:

The chart shows disinflation and is getting worse -- see the
arrow. Currently inflation is running a
little under 1%; thus, we are currently not in deflation, but disinflation. An article in FT
highlights the concern moving forward:
“’The lesson of the past, [CLSA], is that the three previous times the US rate of inflation dropped below 1 per cent since 1957 — 1998, 2001-02, and 2008-09 — stock market investors suffered significant losses.’ …
In 2002, during the period when Ben Bernanke made his infamous helicopter money speech, stocks fell by almost a third after US inflation dropped below 1 per cent.
Also, in 2008, inflation fell through that 1 percent line days before Lehman Brothers filed for bankruptcy.”I decided to dig a bit deeper and put together my own data table – here. I was looking for points in time when inflation for all items (there appeared to be little link between inflation ex. food and energy) was lower than both our current level of inflation and subsequent one year returns. Here is the summary:

To me the data and subsequent analysis shows the following:
- First there is a small sample size, so certainly findings should be taken with a grain of salt.
- Returns are lower and the probability of a negative return over the next 12 months is elevated.
- But the lowest return, while large, still isn’t a bear market and I wouldn’t consider it catastrophic, especially with diversification and risk control.
- And there are still positive returns with some large ones even.
- What’s also interesting is the negative correlation (lower inflation number = higher forward returns), which on the surface seems counter intuitive…
- Until you take into account that as these numbers worsen the Fed will ease more and thus provide a bump to the markets.
- When you look at the 2009 data, this illustrates that. The big fall in the market coincided with disinflation/deflation; however, once we fell below 1% the 12 month forward returns on the S&P were all positive.
- Thus, my view is even if disinflation persists, based on recent history the Fed will step up and pump up the inflation number, and subsequently the market. Now if the Fed doesn’t step up or their efforts no longer work, then the risk of negative returns on stocks is elevated.
The views and opinions expressed herein are those of the
author(s) noted and may or may not represent the views of Capital Analysts,
Inc. or Lincoln Investment. The
material presented is provided for informational purposes only. Nothing
contained herein should be construed as a recommendation to buy or sell any
securities. As with all investments, past performance is no guarantee of future
results. No person or system can predict the market. All investments are
subject to risk, including the risk of principal loss.